


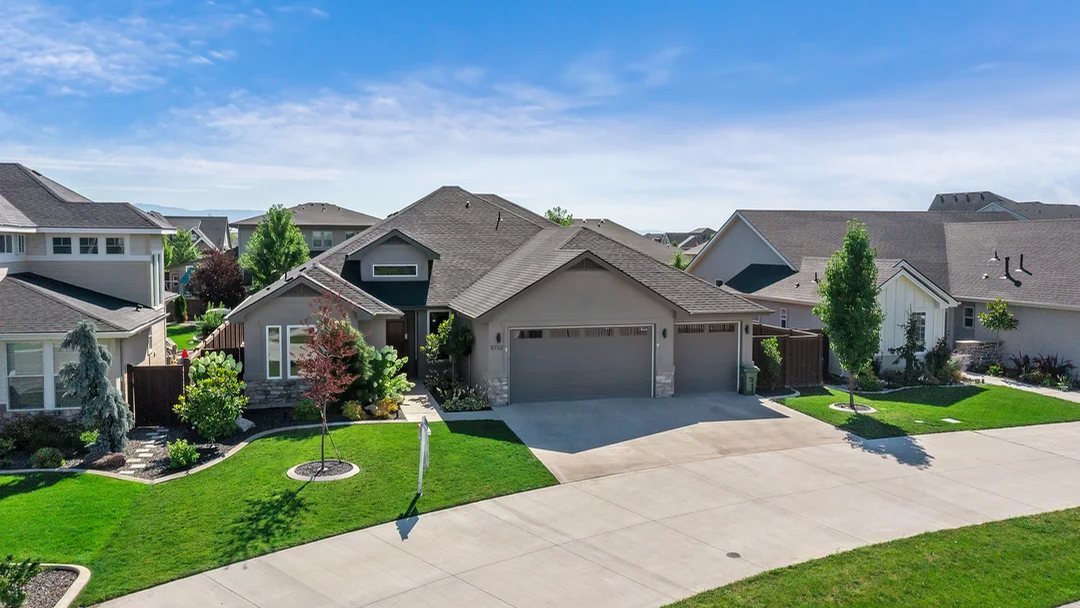
The short answer is yes, for some buyers, and you may have more options than you think.
I've worked in Treasure Valley real estate for more than 30 years, and before I became a Realtor I was an Idaho real estate appraiser. I've watched this market change a lot, and I understand why first-time buyers wonder whether owning a home in Meridian is still within reach. Prices are up, mortgage rates have pushed payments higher, and saving a down payment while paying rent can feel close to impossible.
Here's what experience has taught me: thinking you can't afford a home doesn't mean you can't. Sometimes the answer is a family member. Sometimes it's a financing program. Sometimes it's a lender who knows how to structure your finances differently. Here are two real examples.
What does it cost to buy in Meridian today?
Prices in Meridian have climbed a long way. When I searched the MLS in October, I found only 12 homes for sale in the whole city under $400,000 (here's what that $400,000 buys). Rates matter too: Freddie Mac's national average 30-year fixed rate was 7.18% on November 5, 2026, so the monthly payment is the number to watch.
The typical price is not the lowest price, though, and the right financing strategy can make a big difference.
How grandparents helped their grandchildren buy a first home in Meridian
I recently worked with a grandparent who wanted to buy a home in Meridian for a grandchild to live in. Before helping the grandparents buy it themselves, I suggested something different: have the grandchild and spouse talk with a mortgage lender first and find out what they could qualify for in their own names. If they owned the home, they'd be the ones building equity.
The lender reviewed their income, credit and finances, and the answer was yes, if the grandparents helped with the down payment and closing costs.
That's where the federal gift-tax exclusion comes in. For 2026, the annual exclusion is $19,000 per giver, per recipient. Two grandparents could each give $19,000 to their grandchild and $19,000 to the grandchild's spouse, up to $76,000 in combined gifts within the annual exclusions, as long as they haven't already used those exclusions on the same people that year. Families should confirm the details with their tax adviser.
Suddenly, buying looked realistic. Then we had to compete with five other offers on a home priced in the low $400,000s.
Years earlier, I had helped the listing agent with her very first transaction in Idaho, and she knew how I do business. That relationship helped put us first in line to answer a counteroffer. My buyers accepted it, and they bought the home.
Not every deal works out that way. But after 30 years here, a lot of agents know I follow through and close. Buying a home takes money, and it also takes someone who knows how to get the deal closed.
The biggest first-time buyer myth: you need 20% down
This is one of the most damaging misconceptions I see. A few years ago I worked with a couple who had lived in Oklahoma, where they remembered homes selling for as little as $37,000. They never bought one, because they thought they needed 20% down. By the time they came to Idaho, many homes here were selling around $600,000, and they felt they'd missed their chance.
They had about $30,000 saved. I introduced them to a lender who looked at their whole financial picture and found that paying off their car loan and a few small bills would help them qualify. With about 3.5% down and financing through the Idaho Housing and Finance Association, a first and a second mortgage, they bought their home.
Here's the part I like best. The money that used to go to car and credit card payments now goes toward paying off the second mortgage early. Their goal is to have it gone in a few years, leaving only the main loan.
They didn't need 20% down. They needed someone to show them their options. Every situation is different, and paying off debts can leave one buyer short on reserves while it helps another, which is why a good lender matters.
How much money do you need to buy a home in Meridian?
Here's the down payment alone on a hypothetical $425,000 home:
| Down payment | Amount |
|---|---|
| 20% | $85,000 |
| 3.5% | $14,875 |
| 3% | $12,750 |
Closing costs, inspections and other expenses come on top. Still, $14,875 is a very different goal from $85,000.
The monthly payment matters just as much. With 3.5% down on $425,000, a 30-year loan at 7.25% has a principal-and-interest payment of about $2,798 a month, before property taxes, insurance, mortgage insurance, HOA dues or any second-mortgage payment. That rate is an example for illustration, and your own terms depend on you and the loan program. A smaller down payment can get you in the door, but the total payment still has to fit your budget.
What if family can't help?
Many buyers don't have family who can help, and that's okay. One resource I often recommend is the Idaho Housing and Finance Association (IHFA), which offers down payment and closing cost assistance to qualified buyers. Much of that help comes as a second mortgage you repay, so it isn't free money, and eligibility, income limits and available funding all matter.
Over the years I've seen assistance funds run low, sometimes near the end of the year, and come back later. Have a participating lender check what's available before you count on it, or rule it out. If you're thinking about buying in late 2026 or early 2027, now is a good time to start asking.
Should you buy now or wait?
I don't think everyone who qualifies for a mortgage should buy. One of my first questions for any first-time buyer is how long they plan to stay in the area.
If you expect to move in a year or two, buying may not make sense. There are costs to buy and sell, and a home may not gain enough value in that time to cover them. If you plan to stay five years or more, the conversation changes. I've seen many homeowners build equity they later used toward their next home. Appreciation is never guaranteed, and selling costs come out of your equity, but the long-term view is worth looking at.
My advice to first-time buyers in Meridian
- Talk with a local mortgage lender. Find out what you qualify for before you decide it's impossible.
- Look at every source of help. Family gifts, Idaho Housing programs and other financing options.
- Look at your whole financial picture. Paying down other debts can do more for you than saving a bigger down payment.
- Work with an experienced local Realtor. Pricing, competition, neighborhoods and a strong offer all make a difference.
Most important: the amount a lender says you can borrow isn't always the amount you should spend.
So, is Meridian still affordable for first-time buyers?
For some buyers, yes. For households with limited income, high monthly debts or no access to help, Meridian is harder than it used to be, and I won't pretend otherwise. After 30 years, I see my job as helping people make good decisions. Sometimes that means buying, and sometimes it means waiting.
Frequently asked questions
Is Meridian, Idaho still affordable for first-time homebuyers?
For some buyers, yes. Family gifts, Idaho Housing down payment assistance and paying down other debts have all helped first-time buyers purchase in Meridian, though it is harder than it used to be for households with limited income or high debt.
Do you need 20% down to buy a home in Idaho?
No. Many loan programs allow 3% to 3.5% down. On a $425,000 home, 3.5% down is $14,875, compared with $85,000 at 20%.
How much can grandparents give toward a down payment without using their gift-tax exclusion?
In 2026 the federal annual gift-tax exclusion is $19,000 per giver, per recipient, so two grandparents can give up to $76,000 combined to a grandchild and the grandchild's spouse. Confirm the details with a tax adviser.
It never hurts to have a conversation
There's no charge to sit down and talk about your situation. Maybe we'll find you're closer to buying than you thought. Maybe we'll find a financing option you didn't know about. Or maybe we'll decide now isn't the best time, and if that's the case, I'll tell you. If there's a realistic way for you to buy a home in Meridian, I'll show you how, show you the homes in your budget, and let you decide.
Call me at (208) 409-7653 or book a 30-minute call. You don't need to know whether you can afford a home before we talk. Finding out is why we should talk.
Market figures reflect information published in October and November 2026 and will change. Programs, rates and assistance depend on eligibility and availability. Tax information here is general education; talk to a tax adviser about your own situation.
